Shareholder Remedies: Litigating Fiduciary Breach in the Wake of Corporate Fraud
Shareholder Remedies: Litigating Fiduciary Breach in the Wake of Corporate Fraud
Shareholder Remedies: Litigating Fiduciary Breach in the Wake of Corporate Fraud
When a promoter discovers that a co-director has quietly routed the company’s flagship contract to a rival he controls, or that the books have been dressed to hide a siphon. The client wants the wrongdoer removed, the money returned, and often the wrongdoer prosecuted. The instinct is to file everything, everywhere. The discipline is to recognise that the Companies Act, 2013, read with a decade of Supreme Court jurisprudence, has sorted these wrongs into distinct channels — and that filing in the wrong one squanders the one thing litigation cannot buy back: time.
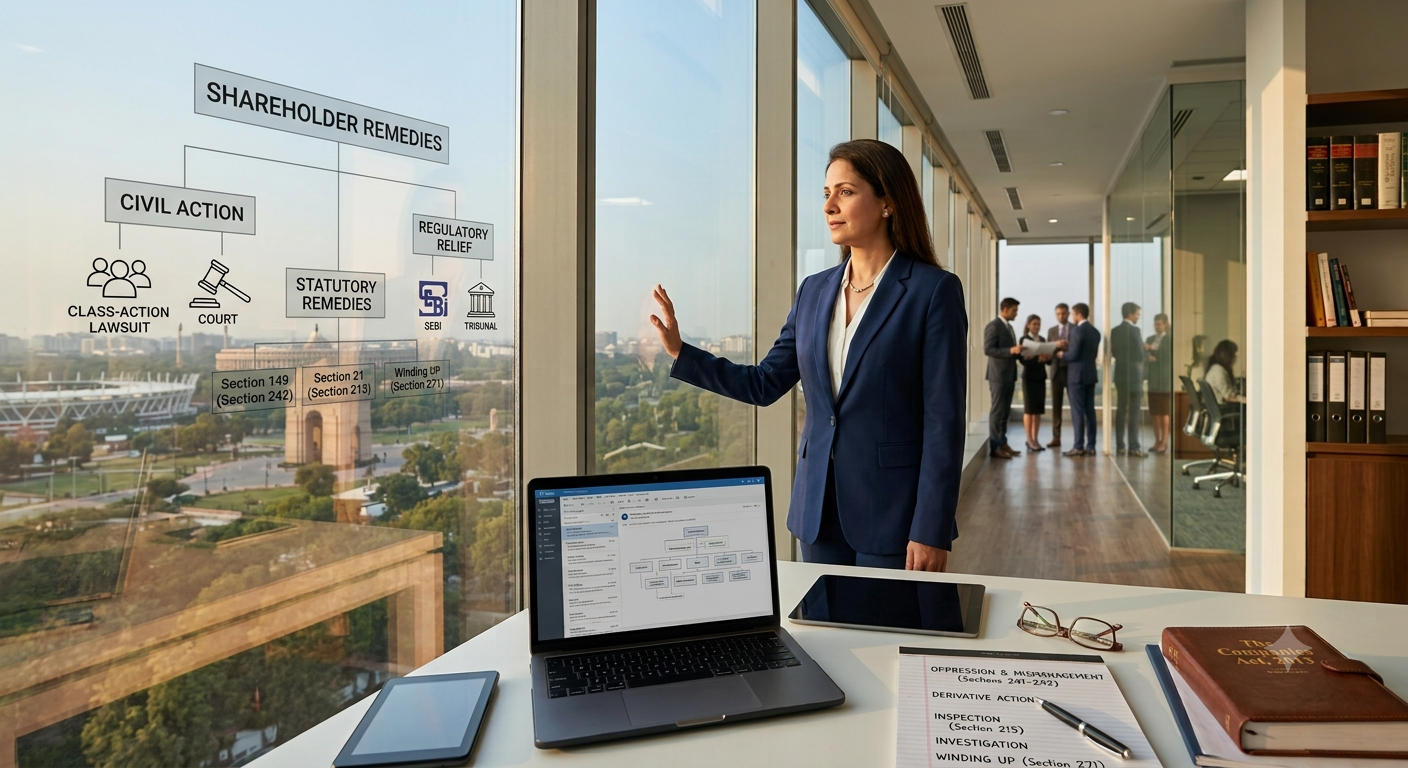
The organising principle is easy to state and easy to forget. The character of the wrong and the relief sought decide the forum, not the label on the petition. A director’s breach can travel two overlapping tracks: a civil-and-statutory track yielding damages, disgorgement and structural relief; and a criminal track yielding prosecution. Within the civil track runs a further fault line — between what belongs exclusively to the National Company Law Tribunal and what a party may lawfully arbitrate. Read the wrong correctly and the map draws itself.
What Section 166 demands
For decades a director’s duties lived in the uncodified common law of trusts and agency, easy to circumvent. Section 166 changed that, crystallising loyalty, good faith, care and the avoidance of conflict into statute. It requires a director to act in good faith to promote the company’s objects for the benefit of members as a whole, to exercise independent judgment with due and reasonable care, to avoid conflicts, and to make no undue gain. Where he does make such a gain, Section 166(5) makes him liable to pay an amount equal to that gain to the company — a statutory disgorgement hook that remains underused.
The courts had already built the scaffolding. In Official Liquidator v. P.A. Tendolkar [(1973) 1 SCC 602], a director who “shuts his eyes” to wrongdoing was denied the defence of ignorance. In Dale & Carrington Invt. (P) Ltd. v. P.K. Prathapan [(2005) 1 SCC 212], the Supreme Court struck down a share allotment engineered to hand a director control, holding that a fiduciary’s powers must be exercised bona fide for the company, never to entrench the fiduciary. The most instructive modern application is Rajeev Saumitra v. Neetu Singh [2016 SCC OnLine Del 512], where a director set up a competing venture and traded on the company’s brand. The Delhi High Court found a clear breach of Section 166, ordered disgorgement under Section 166(5), and allowed a derivative action to proceed where the company, deadlocked between equal shareholders, could not sue in its own name — confirming that the civil court’s jurisdiction over fiduciary breaches runs concurrently with company-law remedies.
These duties are not, however, a charter for hindsight. Needle Industries (India) Ltd. v. Needle Industries Newey (India) Holding Ltd. [(1981) 3 SCC 333] supplies the counterweight: a genuinely bona fide corporate act is not rendered wrongful merely because it incidentally shifts the balance of control. And the duty of care is calibrated to the role — an executive or managing director is held to a higher standard than a non-executive or independent director, the latter of whom can still resist liability by showing that he attended, applied his mind, and recorded a dissent in the minutes. Position alone is neither a source of liability nor a shield from it.
The corporate-opportunity trap
A recurring and fact-sensitive question is how far a director may prepare to compete. The doctrine of corporate opportunity pits a director’s freedom to deploy his own skill and talent against the loyalty he owes while in office. English authority, persuasive before Indian courts, takes a merits-based view: in Foster Bryant Surveying Ltd v. Bryant [2007] EWCA Civ 200, a director who resigned and later competed — without diverting a maturing opportunity or acting dishonestly — was not liable, whereas one who peels away business he was pursuing for the company is. Rajeev Saumitra sits at the culpable end of that spectrum: active diversion during tenure, riding on the company’s brand and resources. The line, in practice, is drawn by honesty and timing. Quiet preparatory steps taken to compete after demitting office may be legitimate; diverting a live opportunity while still a fiduciary is not.
The NCLT’s exclusive turf
Where a fiduciary breach is woven into a broader pattern of prejudicial conduct, the home is Sections 241–242, before the NCLT — whose powers to remove directors, regulate affairs, order a buy-out, unwind transactions or wind the company up are extraordinary. But the standard is demanding. Since Shanti Prasad Jain v. Kalinga Tubes Ltd. [AIR 1965 SC 1535], the conduct must be “burdensome, harsh and wrongful” and generally continuing, and Sangramsinh P. Gaekwad v. Shantadevi P. Gaekwad [(2005) 11 SCC 314] confirms that oppression is never presumed — the burden lies squarely on the petitioner to establish it on the conduct as a whole. In Tata Consultancy Services Ltd. v. Cyrus Investments (P) Ltd. [(2021) 9 SCC 449], the Court held that removal of a director or chairman is not, by itself, oppression unless part of a course of conduct oppressive to members qua members.
Where the injury is not to an individual member but to a class — of shareholders or depositors — Section 245 offers a class action before the same Tribunal, a remedy that remains strikingly underused a decade on; and the Section 244 threshold for standing can itself be waived by the NCLT for a deserving minority, as it was for the minority companies in the Tata–Mistry litigation. It is precisely these sweeping, third-party-binding reliefs that render oppression-and-mismanagement disputes non-arbitrable.
The arbitrability divide — and the fraud saga
Arbitrability rests on Booz Allen & Hamilton Inc. v. SBI Home Finance Ltd. [(2011) 5 SCC 532]: rights in rem are non-arbitrable; rights in personam are arbitrable. An award binds only the parties; an NCLT order under Section 242 binds the company, its members and third parties. That asymmetry is decisive. The Bombay High Court applied it in Rakesh Malhotra v. Rajinder Kumar Malhotra [2014 SCC OnLine Bom 1146], holding that genuine oppression petitions cannot be arbitrated — while arming respondents with a shield: a “dressed-up” petition, a contractual dispute cloaked in oppression to escape an arbitration clause, will be read as a whole and referred to arbitration. The Supreme Court then consolidated the field in Vidya Drolia v. Durga Trading Corpn. [(2021) 2 SCC 1], laying down a four-fold test for non-arbitrability — rights in rem, erga omnes effect, inalienable sovereign functions, and statutorily reserved fora.
The sharpest shift has been on fraud. For years, N. Radhakrishnan v. Maestro Engineers [(2010) 1 SCC 72] was cited for the view that serious fraud could not be arbitrated. That is no longer the law. A. Ayyasamy v. A. Paramasivam [(2016) 10 SCC 386] separated “simple” fraud (arbitrable) from “serious” fraud touching public law (for the court); Rashid Raza v. Sadaf Akhtar [(2019) 8 SCC 710] reduced this to a twin test — fraud ousts arbitration only if it vitiates the arbitration agreement itself or lies in the public domain against the State; and Avitel Post Studioz Ltd. v. HSBC PI Holdings (Mauritius) Ltd. [(2021) 4 SCC 713] established a presumption of arbitrability, holding civil fraud arbitrable and a parallel criminal case no bar. Vidya Drolia and N.N. Global Mercantile (P) Ltd. v. Indo Unique Flame Ltd. [(2021) 4 SCC 379] then expressly overruled N. Radhakrishnan. The lesson for shareholder is blunt: do not concede non-arbitrability merely because the word “fraud” appears in the pleadings or an FIR exists. The dispute leaves arbitration only on the Rashid Raza test, or where the NCLT’s exclusive reliefs are genuinely invoked.
The criminal track — and the discipline of pleading
The criminal track runs on its own rails. Its centrepiece is Section 447, which casts a deliberately wide net: fraud is defined to include any act, omission, concealment of fact or abuse of position committed with intent to deceive, to gain undue advantage, or to injure the interests of the company, its shareholders or its creditors — and, tellingly, the offence is complete whether or not any wrongful gain or loss actually results. That breadth is also the provision’s weakness; the definition strains to draw a bright line, and a bare allegation of fraud, unaccompanied by the requisite dishonest intent, will not sustain a charge. Where made out, the offence is cognizable and non-bailable, punishable with six months to ten years’ imprisonment and a fine of one to three times the amount involved — rising to a minimum of three years where the public interest is engaged.
For serious matters the affairs of the company may be referred to the Serious Fraud Investigation Office under Sections 212–213, whose powers of investigation and arrest were upheld in SFIO v. Rahul Modi [(2019) 5 SCC 266]. Section 447 does not displace the general criminal law; it layers over it — criminal breach of trust, cheating, forgery, falsification of accounts and conspiracy — now housed in the Bharatiya Nyaya Sanhita, 2023, which replaced the Indian Penal Code with effect from 1 July 2024, with SEBI’s PFUTP Regulations biting on listed companies and the Fugitive Economic Offenders Act, 2018 available where the accused absconds with sums of a hundred crore or more.
There is one trap that quashes more prosecutions than any defence on merits: loose pleading against directors. Indian criminal law recognises no automatic vicarious liability. Through Maksud Saiyed v. State of Gujarat [(2008) 5 SCC 668], S.M.S. Pharmaceuticals Ltd. v. Neeta Bhalla [(2005) 8 SCC 89] and Sunil Bharti Mittal v. CBI [(2015) 4 SCC 609], the Supreme Court has insisted on specific, role-based averments that the director was in charge of and responsible for the conduct of the business, or acted with active connivance and intent. A designation on the letterhead is not enough; counsel who arraign non-executive directors without particulars invite a clean quashing. And where the corporate form is itself the instrument of fraud, the veil may be pierced — but only exceptionally, on a strict showing of sham, as Delhi Development Authority v. Skipper Construction Co. [(1996) 4 SCC 622] confirms.
Money laundering and the problem of parallel proceedings
Where the fraud has generated proceeds of crime, the Prevention of Money Laundering Act, 2002 enters, bringing the Enforcement Directorate’s formidable powers of provisional attachment, search and arrest — upheld, along with the reverse burden and the stringent twin bail conditions, in Vijay Madanlal Choudhary v. Union of India [(2022) 10 SCC 1], a regime now itself the subject of pending review. A scheduled predicate offence can thus set an ED investigation running alongside the Section 447 prosecution, the SFIO probe, and the civil or NCLT proceedings — four forums, one set of facts.
That multiplicity is lawful, and understanding it is half the strategy. Civil, tribunal, arbitral and criminal proceedings on the same facts can coexist; each answers a different question on a different standard of proof, and a finding in one does not bind another. Avitel settled that the pendency — or even the institution — of a criminal case does not render the civil dispute non-arbitrable. The practical corollary is sequencing. A claimant who needs urgent structural relief should move the NCLT, or seek interim measures in aid of arbitration, without waiting for the criminal process to mature — while staying alive to limitation, which runs independently on each track and forgives no one for treating the criminal complaint as a substitute for timely civil action.
Bottomline
Diagnose the relief before proceeding with relief. Structural relief means the NCLT and cannot be arbitrated — so plead genuine oppression, not a contract claim in disguise. A clean fiduciary breach that has cost the company money is a candidate for a derivative action and Section 166(5) disgorgement in the civil court. Never surrender arbitrability merely because fraud is alleged; civil fraud is arbitrable, and only the twin test or the Tribunal’s exclusive reliefs take a dispute out of the arbitrator’s hands. Run the criminal and ED track in parallel where the facts warrant — weighing it not only for its own reliefs but for the leverage and reputational exposure it creates, a lever to be pulled deliberately rather than reflexively — and arraign directors with surgical precision. The 2013 Act, read with the Court’s arbitrability jurisprudence, has handed the litigator a rational map: the wrong points to the forum, and the advocate’s craft lies in reading the wrong correctly, and refusing to be lured into the wrong court.